Life Insurance: What to Expect When You're Applying

 November 3, 2025

Thinking of applying for life insurance? One of the realities of the individual life insurance market is that not everyone will qualify for the same rates or coverage levels. But here’s the good news: Even if your health isn’t perfect, chances are you can still find an affordable policy that offers meaningful protection for your loved ones.


Insurance companies want to insure you—just at a premium that reflects your overall risk. That means they look at more than just your health when evaluating your application. Here’s a quick overview of what to expect.


What Life Insurance Companies Review


Your application: The amount of coverage you’re applying for needs to make sense given your income and financial picture.


Your occupation: Some jobs are riskier than others. An accountant might be considered lower risk than a firefighter or construction worker.


Your health history: Certain medical conditions—like a recent cancer diagnosis—can make it harder to qualify, depending on the insurer. But don’t worry if you’re carrying a few extra pounds; many carriers approve applicants who are overweight if they’re otherwise in good health.


Your habits: Smoking will definitely bump up your premium. Illegal drug use is typically disqualifying, though some insurers are more lenient about marijuana, especially as laws continue to evolve.


Your medical records: Insurance carriers may access a central health database that works a bit like a credit bureau for your medical history. This helps them verify the information on your application.


The medical exam: Depending on your age and the amount of coverage you’re seeking, this could range from a quick check-up to a full physical, including labs and an EKG.


Consistency counts: All the pieces—your application, your exam, your records—should line up. If something doesn’t match, like failing to disclose a known condition, it will likely raise questions and slow things down.


Your gender: On average, women live longer than men, and in most states, that can translate to lower life insurance premiums. Some states require gender-neutral pricing, but it's still a factor elsewhere.


The Bottom Line


Life insurance companies aren’t looking for perfect health—they’re looking for transparency and average risk for your age group. If one carrier turns you down, another might approve you. And if you’re rated in a higher-risk category, consider accepting the coverage now. You can always apply again in the future if your health improves.


Making even small lifestyle changes—like losing weight or managing your blood pressure—could help you qualify for better rates down the road. In the meantime, your family will have the peace of mind that comes from knowing they’re protected.


Need help navigating the process or finding the right fit? We’re here to guide you.

Checklist clipboard with blue health and finance icons, including shield, umbrella, charts, heart, and calendar.
September 23, 2026
Retiring soon? Review seven key financial decisions involving investments, Social Security, Medicare, RMDs and retirement income before you retire.
Smartphone on a wooden table showing an incoming call from “Unknown Caller,” with a coffee mug nearby.
September 16, 2026
Medicare scam calls and fake insurance agents are on the rise. Learn the warning signs, how to verify who you're talking to, and what to do if you share information.
Two hands gently holding each other on a soft surface
September 9, 2026
September is Suicide Prevention Month. Learn what to watch for, how to start a hard conversation, and where to turn for help. Support matters more than perfect wording.
Elderly man on a couch holding a phone while an elderly woman in pink leans over to help him
September 2, 2026
Learn how Medicare enrollment can affect HSA contributions, why retroactive Part A coverage matters, and how to avoid potential excess contribution taxes.
Older man riding a red mobility scooter on a park path in autumn
August 26, 2026
aThinking about a wheelchair or mobility scooter? Learn what Medicare covers under Part B, what your doctor must document first, and how to avoid a denied claim.
Three coworkers discussing at a table with a laptop in a bright office
August 19, 2026
Buying insurance online is fast, but a licensed agent can help you compare carriers, understand the fine print, and advocate for you at claim time.
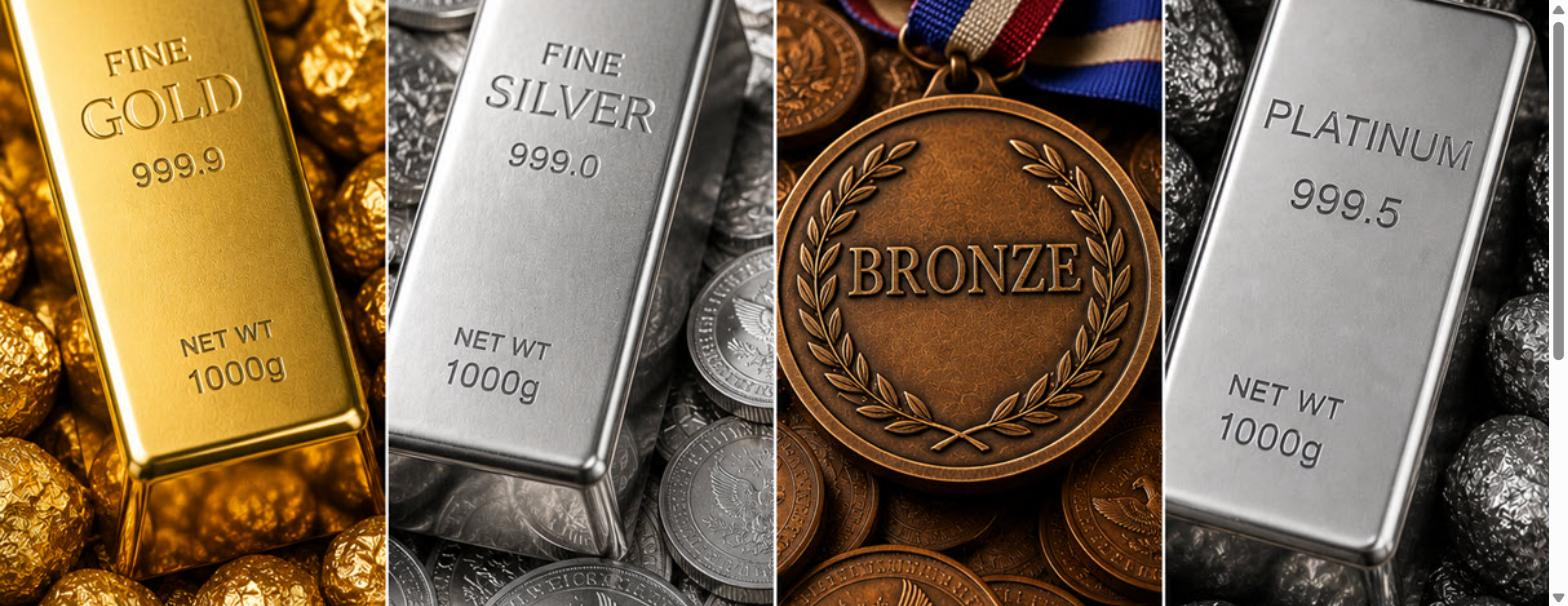
Gold, silver, bronze, and platinum metal bars representing health plan tiers
August 12, 2026
A clear guide to Health Insurance Marketplace metal tiers. Learn how Bronze, Silver, Gold, and Platinum plans split costs and how to pick the right one.
Older couple walking outdoors on a leaf-covered path with a rolling walker
August 6, 2026
Learn how to prepare for health care costs in retirement, including Medicare, retiring before 65, long-term care, HSAs, and supplemental insurance options.
Woman tying a child’s sock while they sit on grass beside a stroller in a park
By Richard Horner • June 24, 2026
Where you go for care can affect your bill by thousands. A practical guide to choosing between the ER, urgent care, telehealth, and your primary care doctor.
Three people sit talking in a cozy living room, looking at a tablet on the coffee table.
By Richard Horner • June 17, 2026
U.S. News & World Report has rated over 12,000 home health agencies. Learn how the rankings work and why they matter for your care and coverage decisions.
Show More